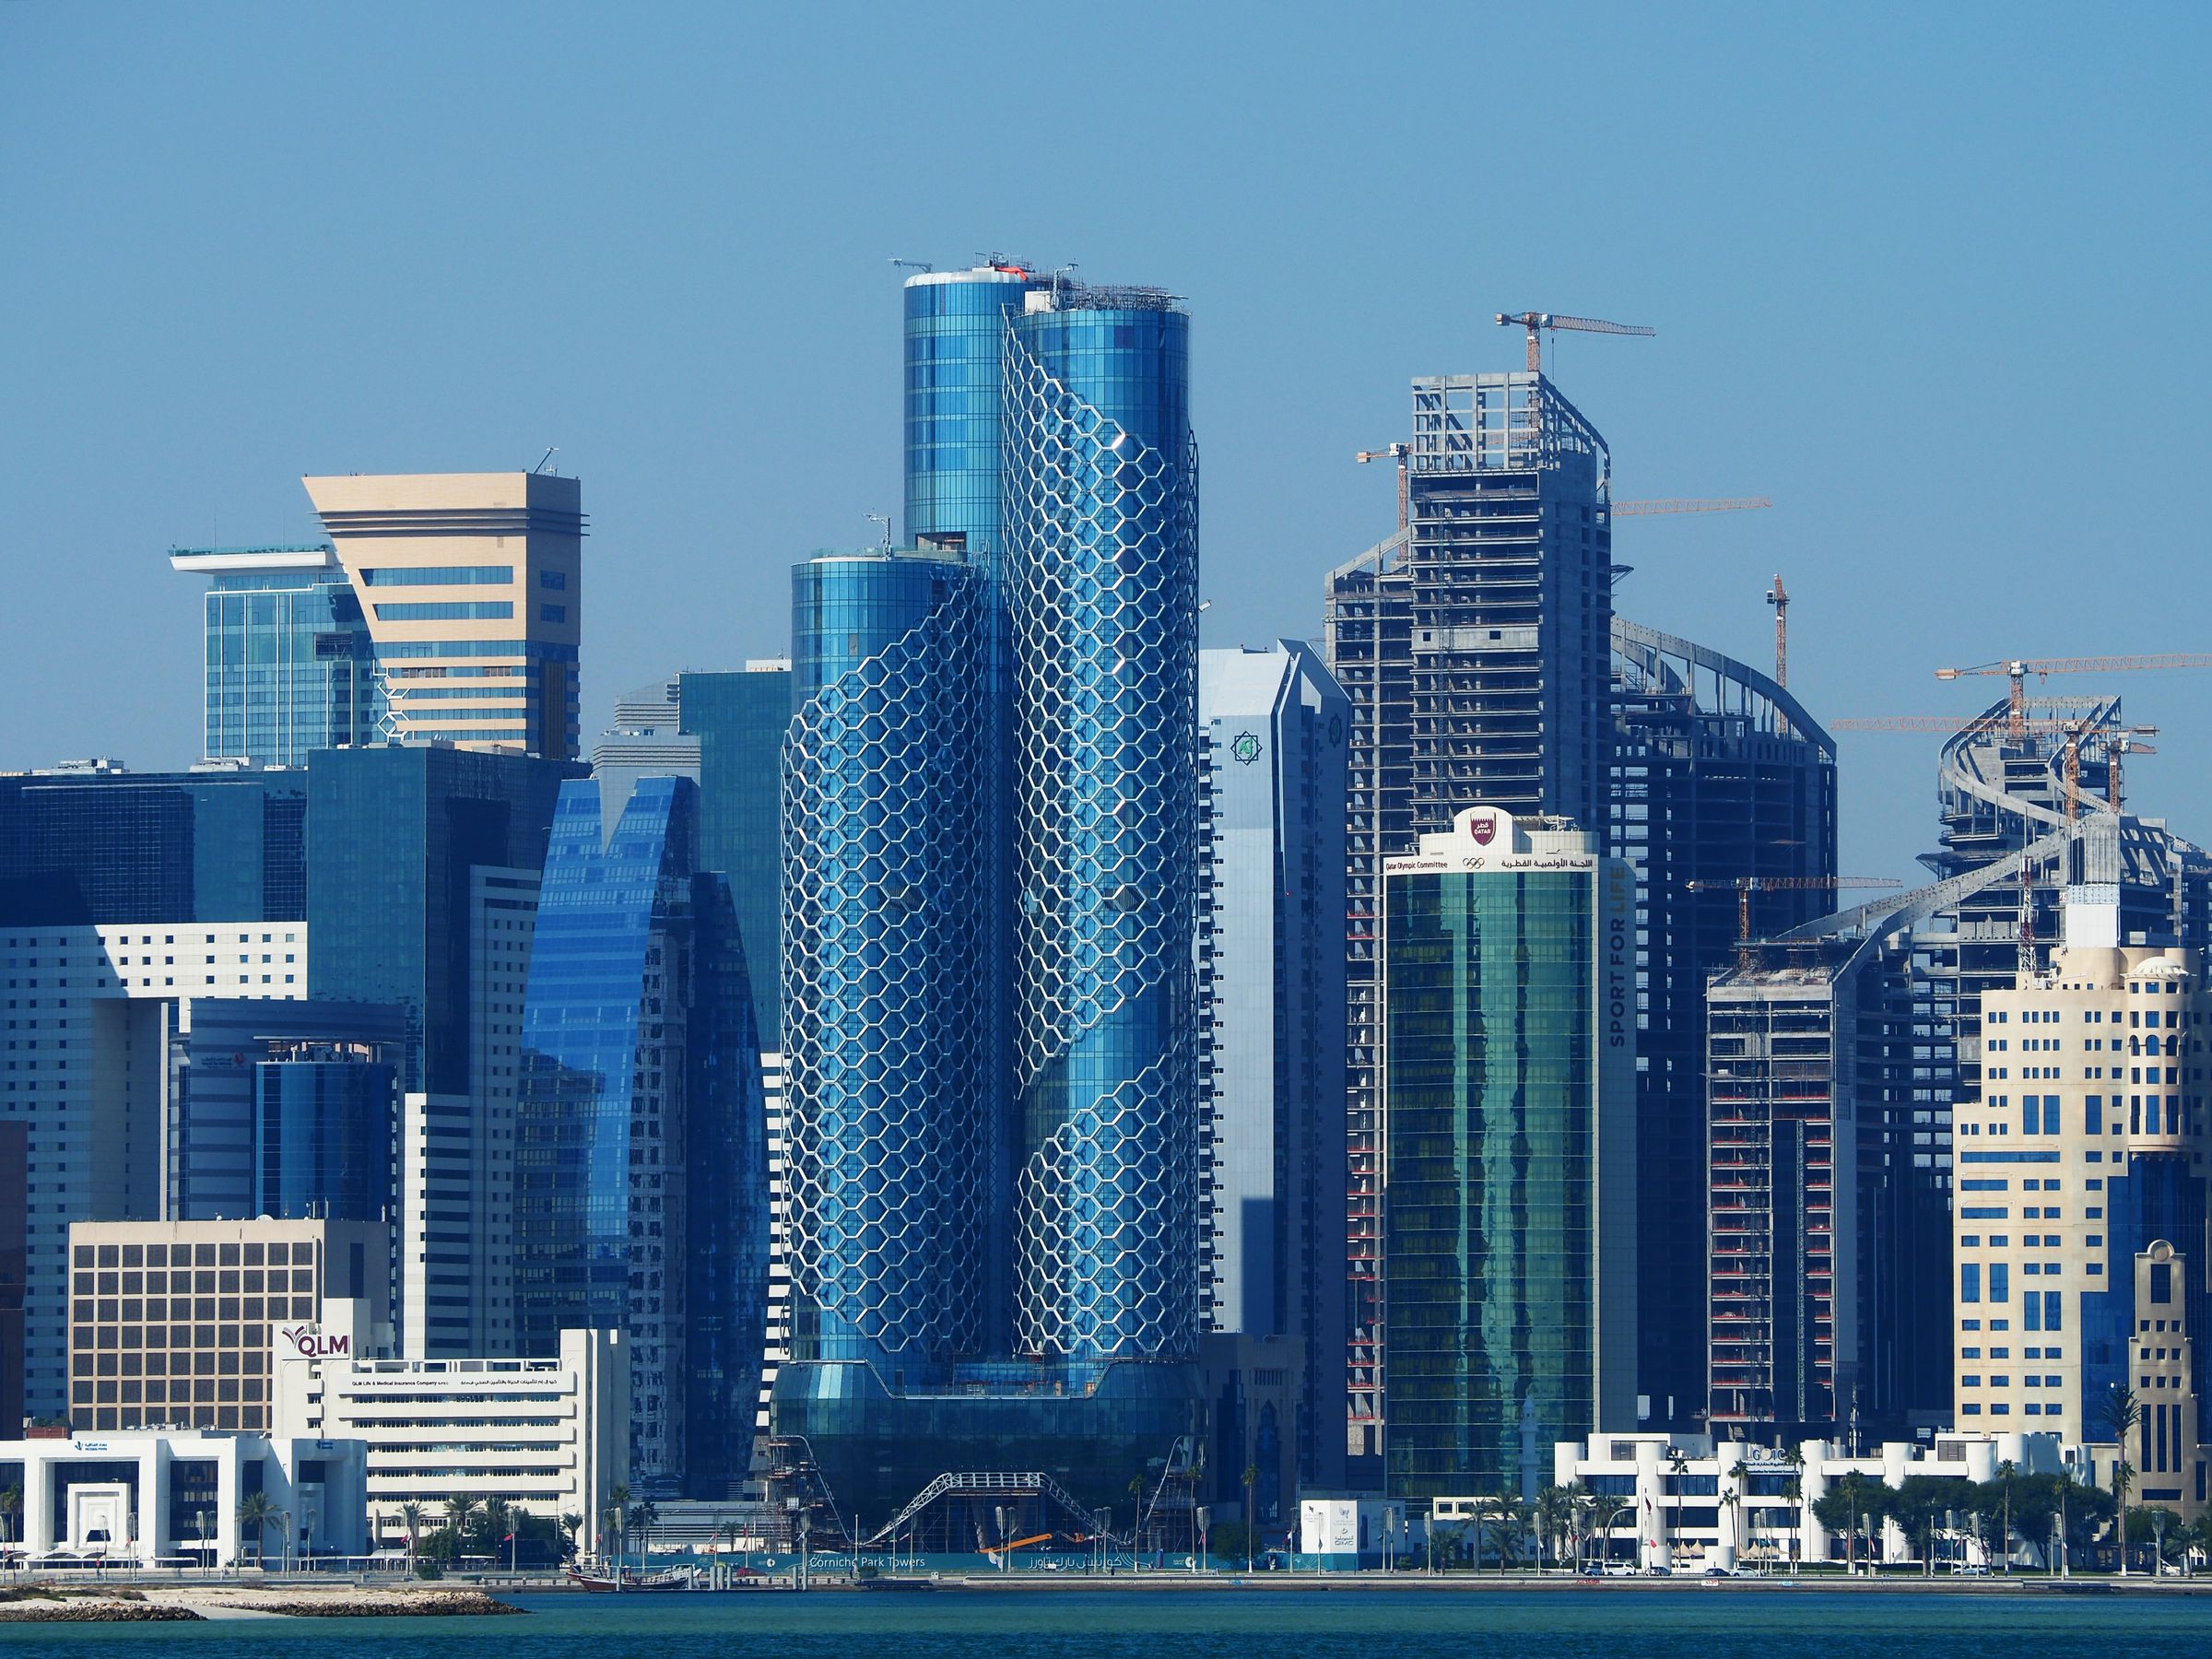
Qatar's State Bank Offers Startups Up to $5.5M Each
State funding terms stay undisclosed as QDB expands its startup programme
Qatar’s state investment machinery has put a price on what it wants from the global tech industry, and that price now runs as high as $5.5 million per company. The offer, administered through the Startup Qatar Investment Program, sits at the intersection of two institutions with distinct mandates: Qatar Development Bank, which deploys the capital, and Invest Qatar, the state investment promotion agency behind the broader Startup Qatar initiative. What neither institution publishes is the term that matters most to any company considering the deal, namely how large an equity stake the state takes in return.
The programme’s structure reflects how the bank has chosen to exercise its mandate. Founders are sorted into two tracks. START, capped at $1.1 million, targets startups with a proof of concept or minimum viable product seeking to establish operations in the country. GROW, capped at $5.5 million, is reserved for established companies, and the bank’s own eligibility notes set the bar explicitly: at least three years of operations under a qualified management team, a positive growth outlook, visible financial stability and an adequate funding history.
Oversight of the money is built into the disbursement model. Funding is not released in a single transfer; the programme page states it is paid in tranches against milestones agreed between the startup and the bank. That arrangement gives QDB continuing leverage over each portfolio company, though the page does not define what constitutes a milestone or what happens when one is missed.
The institutional offer extends well beyond capital. The package includes waived registration and licence renewal fees, flexible work and entrepreneur visas, subsidised co-working space, hiring and internship support, access to research and development grants, subsidised housing, mentoring and exhibition space. When Invest Qatar launched Startup Qatar in February 2024, it also described a five-year tax waiver administered by the Qatar Financial Centre, alongside free registration for the same period. Details of the offer are laid out at https://startupfortune.com/qatar-is-offering-tech-startups-up-to-55-million-dollars-to-launch-or-expand-there/.
The bank has framed its priorities in sectoral terms, directing the programme toward high-growth ideas it believes can add value to Qatar’s economy. The stated list covers AI and machine learning, B2B software, fintech, health, education, climate, energy, agriculture, cybersecurity, robotics and drones, property technology, sports technology, supply chain technology, marketplaces and the Internet of Things. QDB notes the list is not exhaustive and that any innovative startup may apply.
The scale of the commitment has grown quickly. When QDB announced the programme in February 2024, Gulf Times reported caps of $500,000 for startups launching in Qatar and $5 million for established companies expanding there. The current page lists $1.1 million and $5.5 million, and the bank’s later public comments have described the expanded packages as part of a broader push to attract global startups to Doha.
Demand, by the bank’s own account, has not been a constraint. Gulf Times reported more than 1,000 applications within two months of launch. This February, Mohammed Al-Emadi, QDB’s executive director of incubation and venture capital investment, said in comments reported by The Fintech Times that the bank had set a target of 1 billion Qatari riyals for the programme through 2030, roughly $275 million, and that it had received more than 6,000 applications. He added that one third of QDB’s venture capital investments in 2025 went to fintech companies. The Central Bank of Qatar, for its part, aims to license between 35 and 50 fintechs by 2030, giving payments and lending startups a clearer regulatory reason to establish themselves locally.
The accountability gap lies in disclosure. Invest Qatar described the programme in 2024 as a route for eligible startups to apply for equity funding, which means the state takes a stake, yet neither QDB’s programme page nor Startup Qatar’s publishes the size of that stake, the valuation methodology or the investment instrument used. The application form asks how much capital a startup has raised and whether it plans to raise more within three months, but it does not explain how the bank decides. Applicants are notified by email, accepted or rejected, with no timeline given.
Those omissions carry practical weight. Milestone terms determine when cash arrives, and residency requirements shape how long a company must stay. Startup Qatar’s entrepreneur residency requires an endorsement from a recognised local incubator and proof of funds, with overseas applicants showing at least $10,000 in the bank over three months. None of this makes the offer unattractive; up to $5.5 million with visas and housing handled is a serious proposition. But for founders weighing a multi-year relocation, the undisclosed term sheet is the first document worth requesting, and whether QDB will publish it before its 2030 target expires remains an open question.
Q&A
Which institutions administer the Startup Qatar Investment Program?
Qatar Development Bank deploys the capital, while Invest Qatar, the state investment promotion agency, runs the broader Startup Qatar initiative under which the programme sits.
What key term of the funding deal is not disclosed?
Neither QDB's programme page nor Startup Qatar's publishes the size of the equity stake, the valuation methodology or the investment instrument used, even though the funding is equity-based.
What are the two funding tracks and their caps?
START is capped at $1.1 million for startups with a proof of concept or minimum viable product; GROW is capped at $5.5 million for established companies with at least three years of operations, a qualified management team, positive growth outlook, financial stability and an adequate funding history.
How is the funding disbursed and what leverage does the bank retain?
It is paid in tranches against milestones agreed between the startup and the bank, giving QDB continuing leverage, though the page does not define what constitutes a milestone or what happens when one is missed.